Watch on YouTube
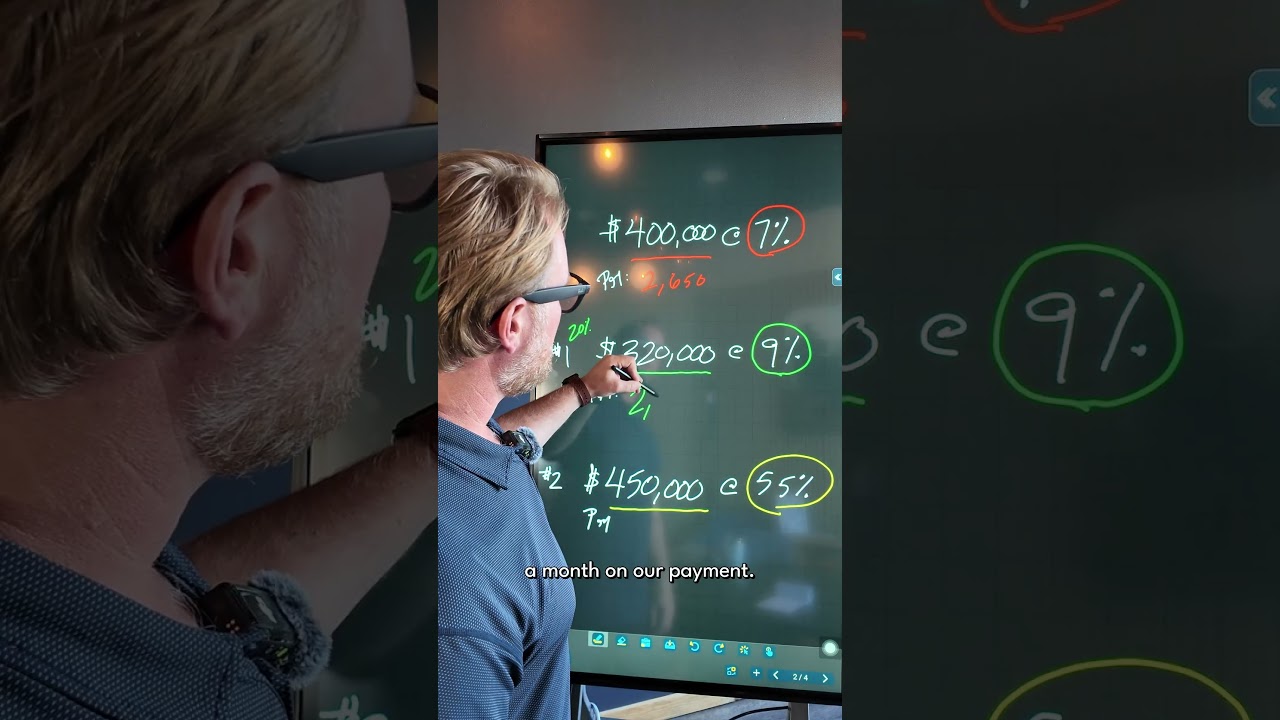
▶ Watch "What If Home Prices Crash 20%? The Math Might Surprise You" on YouTube
Every few months, someone predicts a 20% housing crash is right around the corner. It's a scary number to hear, especially if you're sitting on the sidelines waiting to buy, or you already own a home and wonder what it would mean for you. So let's actually run the math instead of just reacting to the headline.
What a 20% Drop Really Looks Like
Say a home is priced at $600,000, which is close to the statewide Washington average right now. A 20% crash would bring that same home down to $480,000. That sounds dramatic on paper. But here's the part most headlines skip: a price crash that size has never happened outside of a major credit crisis like 2008, and the conditions that caused that crash (loose lending, adjustable-rate loans resetting, oversupply) simply aren't in place today. Lending standards have been tight for over a decade, and most homeowners are sitting on fixed-rate loans well under today's rates.
The Math for Buyers Waiting on a Crash
If you're waiting for a 20% drop before you buy, ask yourself what happens to rates in that same scenario. Home prices don't usually fall in a vacuum. A crash big enough to move prices 20% would almost certainly come with a serious economic slowdown, and that kind of slowdown tends to push mortgage rates around too, not always down.
Here's the real comparison worth making: run your target home price at today's rate through our mortgage calculator, then run a 20% lower price at a higher rate. In a lot of cases, the payment ends up close to the same, or worse. The price on the sign isn't the number that matters. Your monthly payment is.
The Math for Current Owners
If you already own, a 20% drop in value doesn't erase your equity unless you bought very recently with a small down payment. Most Washington homeowners have significant built-up equity from years of appreciation, so a hypothetical drop would mostly eat into recent gains, not put people underwater. It's uncomfortable to think about, but it's not the same disaster it would have been in 2008 for most owners.
Why the Fear Sells Better Than the Math
A scary prediction gets more clicks than a nuanced one. That doesn't mean prices can never soften. Some markets have cooled and some price cuts are happening in pockets across Western and Eastern Washington. But a broad 20% crash requires conditions we simply don't have right now: massive oversupply, risky lending, or a wave of forced sales. None of those are showing up in the data today.
What To Do Instead of Waiting on a Crash
Rather than betting your plans on a crash that may never come, it's worth building a strategy around what you can actually control. Check today's rates so you know where you stand, run your real numbers through the calculator, and figure out what payment actually works for your budget at today's prices and rates.
Not sure where to start? Start here → and let's talk through your specific numbers instead of a hypothetical headline.
The Bennett Team is here to help you separate the scary predictions from what's actually happening in your market, so you can make a decision based on math, not fear.
📲 (360) 739-3454 🌐 applywithrj.com